Skip to content
China Steel Raw Materials: Iron Ore, Coke & Price Outlook Prices
September 23, 2026 | Data as of Sep 22-23, 2026
Key takeaways: China’s steel raw material market showed a clear divergence in September — iron ore pulled back from highs to near year-to-date lows, coke completed a fifth consecutive round of price hikes on cost pressure, and scrap and billet traded in narrow ranges. Raw material costs stayed elevated, while steel mill profitability fell to a record low of 7.79%. With “cost support” battling “weak demand,” steel prices are likely to remain rangebound in the near term.
1. Iron Ore: Pullback from Highs, High Port Stocks Cap Prices
Since early September, the benchmark iron ore futures contract retreated from a yearly high of 745 yuan/t to a low of 704.5 yuan/t, a cumulative decline of about 5.44%. The Platts 62% Fe iron ore index eased from above USD 100/t in early September to 96.65 USD/t (September 21).
The main pressure comes from the supply side: as of September 18, inventories at China’s 47 major ports stood at 171.3593 million tonnes, up 19.15% year on year; global weekly shipments from 19 ports remained near yearly highs, with non-mainstream supply (including Guinea) still ramping up. On the demand side, daily hot metal output at 247 surveyed mills was 2.3763 million tonnes, and pre-holiday restocking is drawing to a close. That said, elevated ocean freight (W. Australia–North China at USD 16.38/t, up 51.9% y/y) and mill restocking provide a floor, so prices are expected to consolidate at low levels in the near term.

2. Coke & Coking Coal: Tight Supply, Fifth-Round Coke Hike Lands
In early September, the average circulation price of quasi-primary metallurgical coke reached 1,983.9 yuan/t, up 12.7% from late August, while main coking coal averaged 2,597.5 yuan/t, up 9.5% — raw material costs clearly outpacing finished steel.
On the supply side, mine safety inspections remain strict and production resumption is slow, while coal truck traffic at the Mongolia border stays low, keeping coking coal supply tight. Facing high input costs, coke plants have actively cut output and kept inventories low, and the market has seen five consecutive rounds of price hikes since mid-August. However, with mill profitability at just 7.79%, mills’ tolerance for high-priced raw materials is fading and resistance to a sixth round is growing — the “steel mill vs. coke plant” negotiation has entered a critical stage.

3. Scrap: Rising Inventories Weigh, Narrow Range Expected
On September 22, SunSirs’ scrap benchmark price was 2,355.50 yuan/t, down about 0.3% month to date. Mill scrap inventories have kept building (Mysteel’s MySSpic absolute price at 2,460.35 yuan/t, mill stocks up to 4.932 million tonnes), with arrivals exceeding consumption and capping prices. Still, pre-holiday restocking ahead of the National Day break and scrap’s improved cost advantage over hot metal — with EAF margins marginally recovering — provide downside support. Near-term scrap is expected to trade in a narrow range (widely expected band: 10–30 yuan/t).、、

4. Billet & Finished Steel: Cost Support vs. Weak Demand
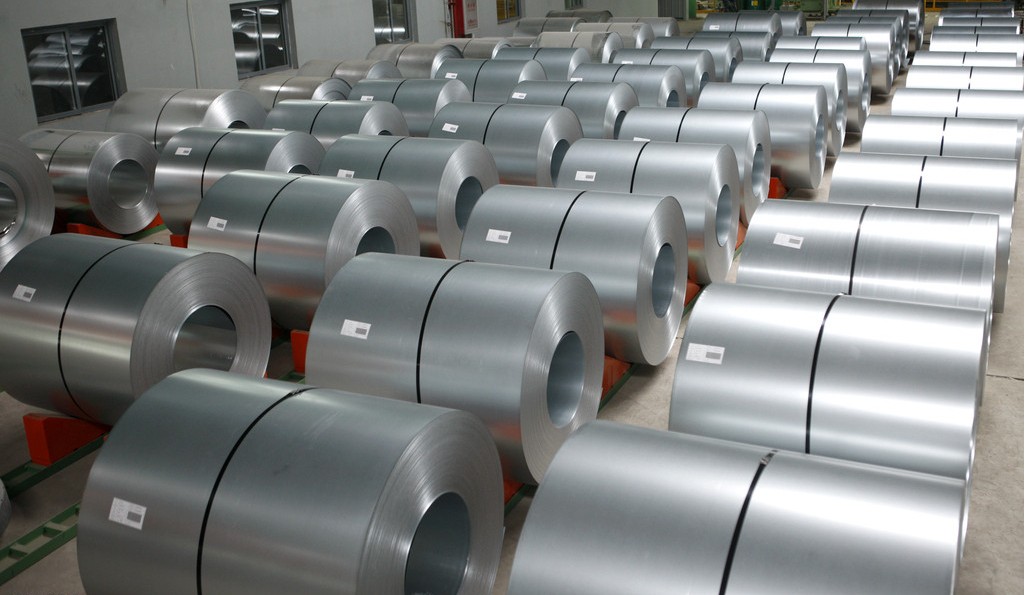
Tangshan plain billet held a narrow band of 3,010–3,060 yuan/t. Finished steel was mixed: hot-rolled coil fell 1.77% month to date to 3,322 yuan/t, while galvanized sheet and color-coated sheet edged up (by 0.66% and 0.76% month to date, to 4,177.5 yuan/t and 6,600 yuan/t respectively), showing flat products were relatively resilient. For steel exporters, elevated raw material costs underpin export quotations, and galvanized/color-coated products have held up better than ordinary long products.
5. Key Data at a Glance
| Product | Latest Price (yuan/t) | Change | Source |
| Iron ore (Australia, 62%) | 700.22 | Flat (Sep 21) | SunSirs |
| Coke (quasi-primary) | 1,983.9 | +12.7% (early Sep m/m) | NBS |
| Scrap | 2,355.50 | -0.3% | SunSirs |
| Billet (Tangshan) | 3,060 | +0.33% | SunSirs |
| Rebar | 3,168 | +1.11% (7-day) | SunSirs |
| Hot-rolled coil | 3,322 | -1.77% | SunSirs |
| Galvanized sheet | 4,177.50 | +0.66% | SunSirs |
| Color-coated sheet | 6,600 | +0.76% | SunSirs |
6. Market Focus & Outlook
- Mill self-discipline output cuts:CISA has urged mills to cut output and destock voluntarily; hot metal output and mill profitability are the key variables for raw material demand;
- “Golden September” demand:pre-holiday restocking has started; whether seasonal demand materializes determines whether negative feedback releases early;
- Sixth-round coke hike:whether it lands depends on mills’ loss tolerance and coking coal cost trends;
- Trade friction watch:Indonesia has initiated an anti-dumping investigation into Chinese galvanized sheet (investigation period up to 18 months) — flat-product exporters should monitor policy progress.
Overall, the market is in a “high cost + weak demand” equilibrium: coking coal and coke costs are prone to stay high, ample iron ore supply caps ore prices, and weak end-user demand limits finished steel upside. In the near term, steel prices are likely to stay rangebound — capped by demand on the upside and supported by costs on the downside. Buyers and sellers are advised to watch mill output cuts and post-holiday demand recovery.
Data sources: SunSirs (100ppi.com), Mysteel, National Bureau of Statistics of China, Platts (via Chuangda Steel Think Tank), Everbright Futures daily report, CSC Steel Weekly, Futures Daily, CMS Futures weekly report, among other public sources. Data as of September 23, 2026. This content is for market information only and does not constitute investment advice.